Investment thesis
Portfolio optimisation — economic intuition. Given a universe of imperfectly-correlated return streams, convex optimisation (Markowitz, risk-parity, recursive decay) produces weights that dominate naive equal-weight on a risk-adjusted basis. The edge is not in alpha discovery but in the disciplined combination of existing signals — consistent with institutional multi-manager allocation.
Risk-adjusted performance — live track record
Forward-tested daily against live market data. Metrics derived from end-of-day portfolio marks; methodology documented on the Due Diligence and About pages.
| Return | Value | Risk-adjusted | Value | |
|---|---|---|---|---|
| Current portfolio worth | $10382.29 | Sharpe ratio | 0.53 | |
| Total return | 3.82% | Sortino ratio | 0.47 | |
| CAGR | 7.78% | Calmar ratio | 0.42 | |
| Volatility (annualised) | 17.60% | Profit factor | 1.14 | |
| Days live | 122 | Maximum drawdown | -18.70% |
Process consistency
| Positive months | 50.0% |
| Best month | 13.11% |
| Worst month | -11.94% |
| Recovery from max drawdown | still underwater |
Market independence and alpha
Measured against every benchmark over the strategy’s own live window. Alpha is annualised Jensen’s alpha (the return not explained by benchmark exposure, assuming a zero risk-free rate); t is its t-statistic.
| Benchmark | Correlation | 90-day rolling correlation | Beta | Alpha (ann.) | t |
|---|---|---|---|---|---|
| SPY | 0.52 | 0.49 | 0.73 | -18.02% | -0.83 n.s. |
| QQQ | 0.68 | 0.64 | 0.60 | -22.29% | -1.20 n.s. |
| FTWD | 0.52 | 0.46 | 0.89 | -20.75% | -0.95 n.s. |
| GLD | 0.12 | 0.09 | 0.09 | +9.85% | 0.39 n.s. |
| BTC | 0.00 | -0.09 | 0.00 | +9.35% | 0.37 n.s. |
Correlation materially below 1.0 to all benchmarks indicates returns that are not a re-expression of long equity beta — a strategy tracking one index closely while showing low correlation to another is not diversifying, only rotating.
Closest benchmark: QQQ (correlation 0.68). Alpha against it is -22.29% annualised but not statistically significant (|t| = -1.20 < 2), meaning it cannot be distinguished from zero at this sample size.
Trading activity
Ratios computed over calendar days understate strategies that hold cash and overstate those that simply trade rarely, so exposure is disclosed directly.
| Lifetime executed trades | 49 |
| Days with no position change | 37.2% |
| Sortino over active days only | 0.59 |
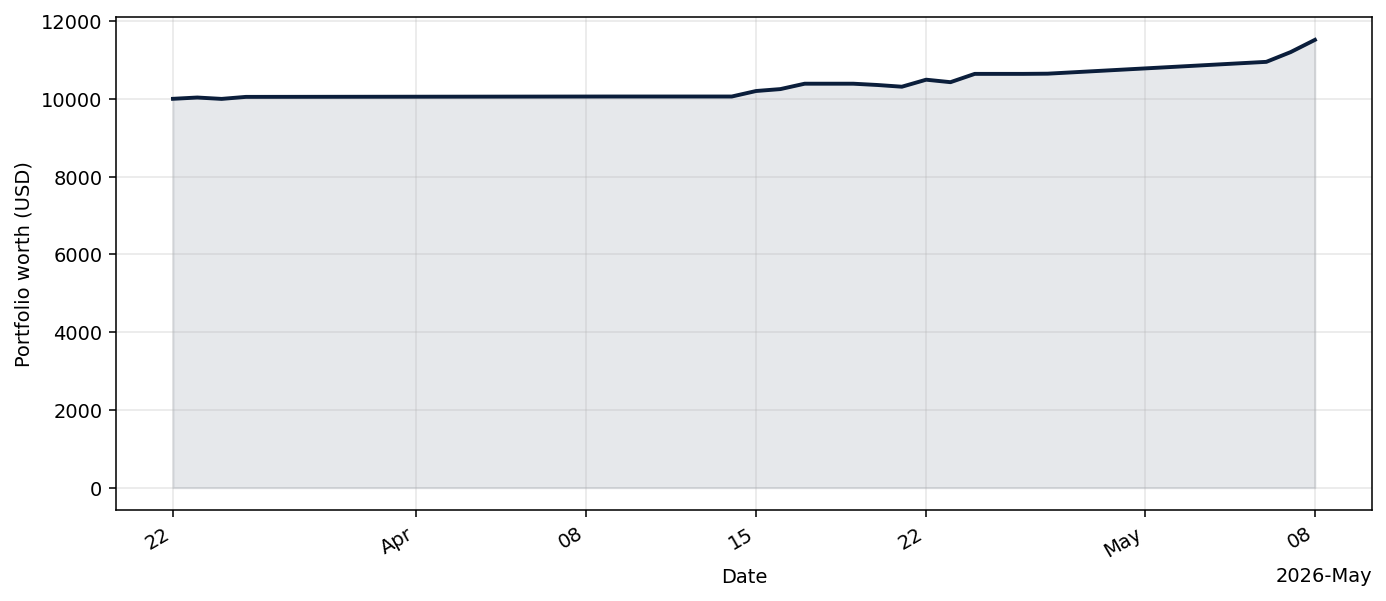
Equity curve
Live track record — forward-tested performance from the strategy's production start date.
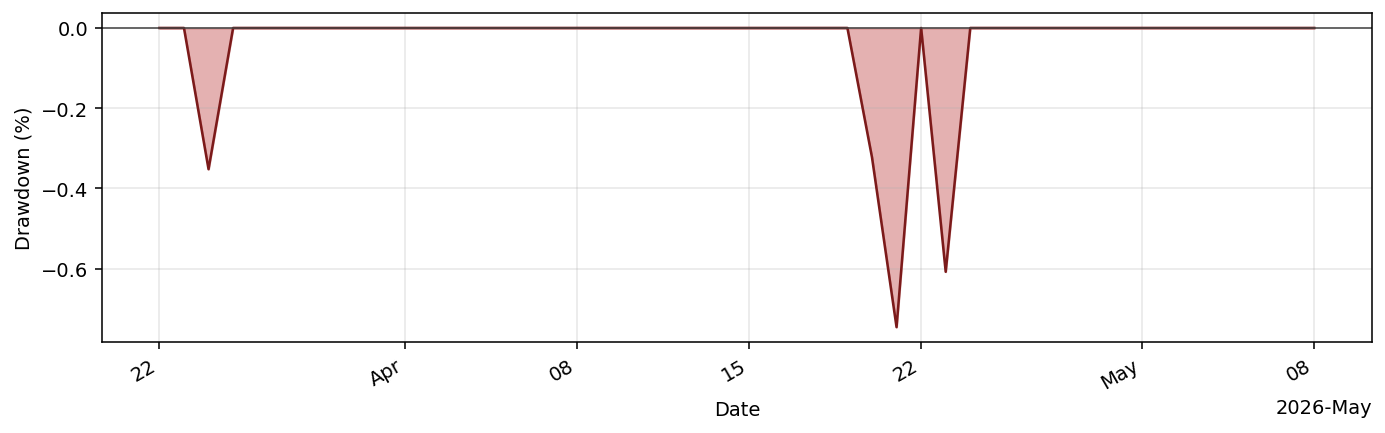
Drawdown profile
Underwater curve — percentage below the running high-water mark. Institutional allocators read this before the equity curve.
Current holdings
| Symbol | Quantity |
|---|---|
| TQQQ | 41.1455 |
| USD | 7135.0880 |
Research & documentation
- Strategy deep-dive: SynthesizedHyperConvexityBot: strategy deep-dive & live performance
- Methodology write-up: SynthesizedHyperConvexityBot
- Reference implementation:
tradingbot/synthesizedhyperconvexitybot.py - Framework: python_tradingbot_framework (open source, fully inspectable)
Related strategies
Other strategies in the Portfolio optimisation family:
- SharpePortfolioOptWeeklyBot · research note- RecursiveDecayHarvestBot · research note Or view the full strategy roster.
For professional investors
Request the investor deck, DDQ, and extended analytics. Firm-gated and reviewed manually.
Request access